The continued lowering of interest rates over the last couple of years was a bit of a salve to a car market stretched by supply shortages, trimflation, tariffs, and other pressures. While buying a car hasn’t gotten dramatically cheaper, it’s still been feasible. How will rate increases hit affordability?
If yesterday’s Morning Dump was an attempt to see the light at the end of the tunnel, today’s TMD is a little more focused on the tunnel itself. A rate hike is basically the last thing anyone wants, even if it’s the sensible thing to do given market conditions. And, wow, market conditions are bad. There’s a new editorial out that enumerates all of the problems.


It could get worse, right? The car industry in Germany is what it looks like if it gets worse. And who is waiting in the wings? China, of course.
The Ripple Effect Of Rate Hikes Is Real
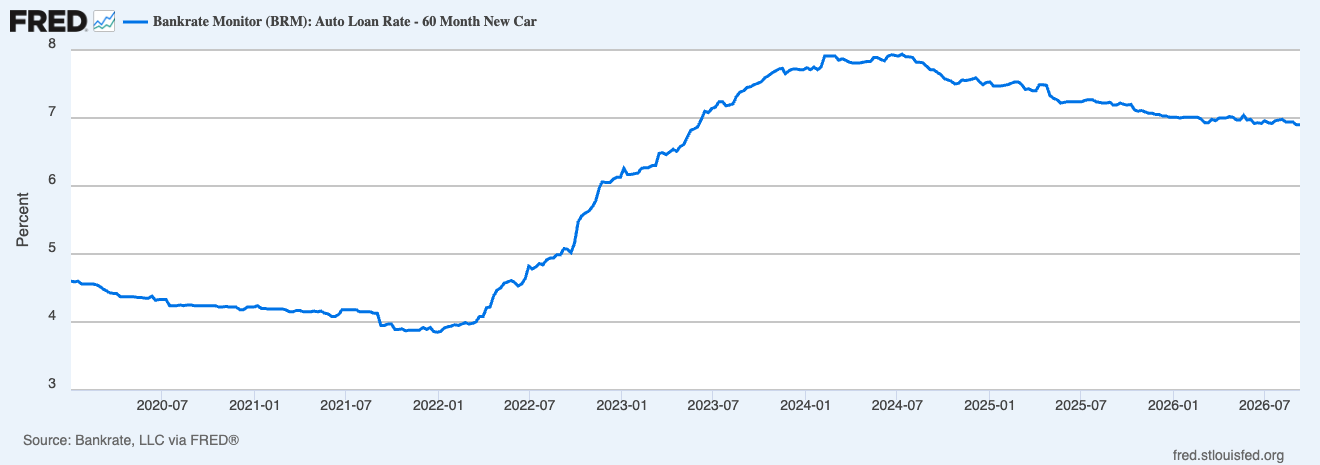
Above is a graph, via my dear friend FRED, of the Bankrate Monitor Auto Loan Rate for a 60-month new car loan (specifically, a $33k loan for someone with a 700 FICO score and a 10% down payment). You can see the impact of pandemic era interest rate policy, as well as the large climb as the fed attempted to fight inflation.
Also at play are the last couple of years of small rate cuts from the Federal Reserve as it had to contend with an economy where nothing feels like it’s getting cheaper, and with an AI development boom that has overheated markets. The Federal Reserve’s Federal Open Market Committee (FOMC) unanimously approved a 0.25 percentage point increase to the federal funds rate (the amount charged by banks to loan excess reserves to other banks).
Here’s what the FOMC said:
Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little.
Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability.
The FOMC wants to keep the economy growing and unemployment low, but it also wants to do so while holding the line on inflation. While this rate doesn’t directly tell a lender what it can charge for an automotive loan, it eventually does impact how much it costs to lend/borrow money. If the fund rate is super low, lenders can generally afford to lower the rates for borrowers.
Obviously, carmakers can lower the price of loan whenever they want via captive financing arms, and will sometimes offer 0% financing if it’s determined that the cost/risk of the loan is offset by the value of selling the car. The chart above is just an average, as your own individual rate will depend a lot on your credit score, your down payment, and general market conditions.
This hike could hit the car market twice. The most obvious impact is on buyers, who could see borrowing costs start to creep up again. What car buyers often forget is that dealers are also borrowing money for the cars in their showroom (this is called a floorplan loan). That’s both good and bad. If dealers have to pay more to keep a car on the floor, they’ll try to capture that extra cost in a sales price. At the same time, a dealership may be more motivated to move a car before it has to pay more to keep it in inventory. If rates go up and remain elevated for long enough, this can lower the number of cars dealers want to order, which then causes prices to go up.
Dealers and automakers want to shield buyers from this as much as possible, and they have some tools, as our pal Jessica Caldwell tells Automotive News:
The Fed’s rate increase will not ease auto affordability challenges, but seasonal rate promotions toward the end of the year could balance out the impact, Caldwell said. It’s difficult to know, however, whether or how much consumer or political pressures factor into the Fed’s rate decisions.
“Affordability is at the top and center for most American families,” she said. “Having an interest rate hike isn’t good optics.”
Even if automakers can offer lower financing, and are willing to absorb the risk/cost, the fear is that consumers will hear the words “interest rate hike” and immediately shy away from dealers even if some are offering good rates.
Here’s A List Of All The Challenges Facing The Car Market
The Automotive News Editorial Board has decided to weigh in on whether or not Widow’s Bay is a comedy or a drama and, as good people, have agreed that it’s obviously a comedy. Oh wait, never mind, they are responding to the interest rate hike by reminding everyone of how tough it is out there.
In addition to the rate hike, other problems include:
- A monthslong war in the Middle East limits access to global crude oil supplies.
- A yearslong war in Europe disrupts global diesel refining capacities and drives up fuel costs for goods deliveries worldwide.
- The U.S. administration has abandoned decades of free trade philosophy, imposing protectionist tariffs on allies and adversaries alike.
- Unprecedented private-sector borrowing to fund artificial intelligence data center build-outs drives up capital costs for all debtors — including the federal government, which hasn’t balanced its own budget in 25 years.
Does the Board suggest a solution? It doesn’t. The enumeration of problems is enough. It could be worse though; we could all be living in Germany.
The German Car Industry Must Hang Together Or Surely They Will Hang Separately
Almost exactly two years ago, I used a TMD to ask “How screwed is the European car industry?” and the answer seems to be: still pretty screwed. And that was before tariffs. Germany is in a particularly rough way, with a new report from Manager Magazin indicated that Germany could lose tens and hundreds of thousands of jobs in the coming years.
Is there a way out? If so, it’ll require some interesting cooperation:
Mercedes CEO Ola Källenius (57) had a surprising message. He told the parliamentary group leaders of the CDU/CSU and SPD, who had invited him to their two-day workshop in Münster at the end of August, that he had always been a bit of an economic policy freak: a believer in the free market, no friend of subsidies. But now he had changed his mind: “This can’t go on,” one participant quoted him as saying.
Together with IG Metall chairwoman Christiane Benner (58), Källenius was to brief members of parliament on the situation of the German automotive industry. Unusually united, the two advocated for industrial policy support during the meeting; the state should help the companies. And they were heard. In the four-page resolution paper that the politicians ultimately agreed upon, there are 20 lines entitled “We remain a car nation”: The federal government will therefore strongly advocate for “local content quotas” for cars sold in Germany and Europe, for continued sales promotion of electric cars and models with partially electric drives, and even announced an explicit “commitment to a technology-neutral transition” within the EU.
Everyone loves the free market when the invisible hand is passing out money, and a little less when it’s handing out slaps.
All Your Factories Are Belong To BYD

You know who might want all of that excess European factory capacity? A little company called BYD, according to Bloomberg:
The manufacturer is targeting three vehicle assembly factories as well as one electric-vehicle battery plant in the region, Alfredo Altavilla, a former Fiat Chrysler manager who advises BYD in Europe, told reporters at an event in Turin late on Wednesday.
“This is not for tomorrow morning, but it’s clear that to reach the volume objectives we have and at the same time become compliant with EU rules, this is what we’ll need,” Altavilla said.
BYD has been holding talks with European competitors and governments as it explores taking over underutilized factories in countries including France, Spain and Italy. The European Union has introduced tariffs on Chinese-made EVs and the bloc’s proposed “Made in Europe” rules are expected to increase pressure on BYD to bolster capacity in the region.
It’s quite the bargain for countries, though it’s easier for the ones who don’t rely on China as an export market.
What I’m Listening To While Writing TMD
Feeling Bay Area today, so please enjoy “Feelin’ Myself’ from the too-soon-gone Mac Dre.
The Big Question
What’s the highest interest rate you’ve paid for a car?
Top photo: FRED, Honda


TBQ: Comedy
So much winning! Are we tired of winning yet?! All’s going according to plan. The Epstein class doesn’t want you to own a single damn thing and within the next 5-10 years it’ll be reality!
This is one of the reasons I have been into owning and maintaining older, but popular (parts supply is important..) cars. Even then, this hobby is awful with the costs.
Great choice with Mac Dre!
About 3%. On a 3 year loan. I paid that off quickly. Making decent money and wanted a fuel efficient car for a job that involved lots of travel.
Back in the late ’90s I agreed to take a car loan out at some crazy rate like 13%, but the car only cost $3500 and I paid off the loan after 2 months. I was just out of school and needed to build credit. Not sure how effective it was, but seemed OK at the time.
So when rates drop does that mean prices drop too?
Nope. Didn’t think so.
Hah you’re a funny one. Lower interest rates means they could just increase prices more
Precisely.
The ONLY thing that drops prices is increased supply and lower demand. Which of course is the real reason for tariffs, the chicken tax, US only emissions and safety regs, etc.
I think my highest rate was around 8 or 9% in the early 90s. I’ve recently started looking at car loan interest rates as they relate to inflation and expected market returns. If I can get a car loan at 4% and expected return on money in a brokerage account is 8%, then I can match or beat inflation depending on what the rate of inflation is. In that case, I’ll carry the loan and put the money in a brokerage account. If inflation climbs or the expected market rate drops, then any extra money goes toward the car loan for the given time period. Granted, I’ll likely only end up a few dollars ahead at the end of the loan, whether it’s paid off early or not, but I would rather have it than give it to the bank.
What brokerage account is paying 8% because I have some money I want to park there.
Looking at average. FXAIX is up over 10% so far this year. Looks like it’s down today, likely on the interest rate announcement.
TBQ:
Flippant answer, but I honestly don’t recall because it’s been 10 years and the loan was paid off at year 4.
Auto loan interest rates matter far less than mortgage rates where a percentage point can result in several hundred dollars difference a month…for 30 years. A 5.5% vs 3.5% rate on a $40,000 auto loan is forty bucks a month on a ~$750/mo payment. The $750 is the worrisome number there rather than the $40.
very true. Same for people making decisions based on the price of gas. Even a huge jump in price is gonna be less than $100 extra per month for most people. Not nothing, but if your payment is $1,000+, it’s not the fuel cost that’s your problem.
When people are chasing low monthly payments on a 96month Stellantis Ram or GM truck loan?
I worry what the impact will be: longer loans, or a drop in truck sales?
Only bought 2 cars on credit the last 50 years. Both were Toyotas.
One new in 1990.
Only new car we ever bought
One used in maybe 1988.
Have no recollection if what the interest rate was now.
Thankfully my wife was great with money and somehow found a way for us to establish credit and build upon it despite a limited income.
But we are WINNING the inflation war, and gas is now under 2 bucks a gallon right?
And my grocery bills have gone from $400 a month to $600 in the last two years.
Thanks to the big orange fat guy…/S
What a total shit show we are living in, again…
January 2029 can’t arrive soon enough.
Well, if you add in the 30%+ inflation since 2019, we’re kind of close to $2/gallon? As long as you pretend wages have also gone up 30%+.
No way that Accord can handle that sort of change in grade with that front overhang. I call shenanigans!
Maybe it’s bendy like the Batmobile in Batman The Animated Series.
Just going to respond to that by saying Batman The Animated Series is excellent. Especially for a 90’s superhero cartoon.
I Agree. I own the set on Blu-Ray. Bruce Timm referred to it as bendy on one of the commentary tracks in the title sequence where it literally bends around a curve.
hence why the industry is so screwed.
“The Big Question:
What’s the highest interest rate you’ve paid for a car?”
My little brother once paid 21% interest back in 1991 when buying a used Cavalier after he got back from USMC basic training and really needed a car. His previous car had been repossessed so his credit rating was crap.
He later traded it for a Jeep Cherokee at a better interest rate, then traded the Cherokee for a Neon because he wanted better gas mileage for his drive from the midwest out to San Diego.
The age callouts – is that normal for business magazines? German magazines?
0% is the only interest rate I will buy a new car at. So either a promotional deal or cash.
The only thing that kept inflation at bay was cheap imports, immigrant labor, and relative stability in the Middle East. And this administration has taken a shotgun to all 3.
Careful there. A few years ago when I was buying, incentives took maybe $8K off MSRP. I asked about the 0% APR offer. Dealer said that made the incentives go away (the interest savings was nowhere close to the discount). Point being, make sure you understand the what trade-offs there may be.
Yep, the 0% offers typically wipe out any other deals that may be on the hood. It’s very frustrating.
What the Fed is not outright saying by raising rates is that wages are not keeping up with inflation, and that these conflict impacts are not temporary.
All of which, we already know.
only if you focus on non-CEO wages.
Non-CEO wages representing.
I should be clear I was being sarcastic. The top is doing just fine, while the other 99.9% are getting screwed.
“he had always been a bit of an economic policy freak: a believer in the free market, no friend of subsidies. But now he had changed his mind..”
Gee, rich free-marketeer starts losing money/faces competition and suddenly his oh-so-prinicipled tune changes real quick, go figure.
Anyway, I was buying a Nissan truck in maybe 1994 and the finance guy and me were going over the terms. He wanted to charge maybe nine percent interest, which I balked at. He got kinda bitchy about it and I think we settled at eight, me being quite the negotiator.
Oh, and when I bought my CPO Sonata, in 2017, I got it at 3.45%.
I just financed a small amount at 6%, which shocked me since I have a credit score over 800.
Fortunately for me, I only financed it to get a slightly better deal, and will pay it off when the first payment is due.
Good credit = zero interestGood credit = prime rate
Too many comments on here from people thinking you get low interest with a good credit score. Not true. You just get closer to the prime rate. Which, could be low interest, or it could be very high interest (but lower than someone with bad credit).
I’m tired Boss.
I dont see any quick end to the current Iran crapshoot. Both sides seem very much the dont take no for an answer when it comes to negotiating. So gas/oil/petroleum prices will keep rising. And so will everything that uses diesel and fuel oil to move. SO, EVERYTHING.
And now pipelines are getting attacked too. Other former old site alums at The War Zone have some good coverage keeping up to date.
It kind of sounds like the Federal Reserve that the Iran conflict will continue well into next year. Ugh.
Yep. And considering the threats to tear down the Kennedy Center because he cant put his name on it, a mea culpa isn’t in our cards. And the other side prepared for almost 50 years now for the exact scenario that we walked right into.
TBQ: What’s the highest interest rate you’ve paid for a car?
When I purchased my Supra 6MT in August 2024 I had a loan at 5.05%, the highest I’ve ever had. Thankfully I had been saving up to buy a car for several years and only needed to finance 25% of the total purchase price (I had originally planned to buy a GR Corolla and saved enough to purchase outright, but decided at the last minute to go for a Supra and needed to supplement my savings). It was a 3-year loan that I paid off in under 18-months.
I’m keenly keeping an eye on prices and rates as my wife’s Touareg will be replaced sometime before Summer 2028. I’m not currently in love with the prices, and rates of the leading contenders, but fingers crossed some price pressure helps things.
One thing the Automotive News editorial didn’t address was the injection of uncertainty into the economy.
When everybody from consumers to corporations to major investors see coherent policies and consistent leadership, even if they don’t agree with everything, they can plan for it.
Could we see another war? A takeover of the Fed? A massive escalation of tarriffs? Who knows. So the response becomes pulling back, shrinking investment, blind gambling, and confused planning all across the economy.
One thing editorial boards can do is be blunt that we need rationality and planning at the top, and instead we get confusion, napping, and vibes.
don’t forget default….
By historical standards, the federal funds rate is still low. We’ve had a whole generation grow up with low rates from the dot com collapse, the housing market collapse/great recession, and COVID.
Has Trump commenced ranting on untruth anti-social about the increase yet?
I have an 800 credit score but the best I could do for a used auto-loan 6 months ago was around 6% from my credit union. I opted to buy outright which is the first time I have ever been financially able to do that. My previous auto loan for 0% for 60 months.
You know he did and demanded rates be absurdly lowered to under 1%
The US and perhaps global economy are on the verge of collapse. At this point close to 50% of all economic growth is tied to Ai while at the same time Ai is the leading cause of job losses over the past 5 months.
Its now $10 a gallon for diesel in California. Any and everything that you buy will continue to skyrocket in expense. Because almost all of it is delivered via ships, trains and trucks that use diesel.
And when that collapse happens? All of the companies that didn’t want to be the first to do the nasty thing by replacing as much of their workforce with Ai will have a ripe opportunity to lay off their workforces and simply never rehire, instead replacing it all with Ai. This week close to half of my entire team at work was left go. Because of Ai. This trend will accelerate and impact a wide swath of industries.
The US automotive industry along with Germany’s will ultimately fail to compete with Chinese brands. And our beloved orange shitstain in chief just made that outcome a lot more easily attainable here in the US because we for whatever stupid ass reason are in a trade war with Canada.
But OTOH…. who will be able to afford these cars? And its batshit insane that even now the two best selling vehicles in the US are full sized trucks. Like how does that work?
I understand that the cost of diesel is directly tied to the cost of goods due to transport of both raw materials and final goods. However nobody has sufficiently explained the ACTUAL PERCENTAGE that this increase represents on ANYthing that I purchase. If diesel fuel has doubled that obviously doesn’t mean my tomatoes or shoes or roofing material or cost of a new car should anywhere near double for example.
What it will or should do is make people (or manufacturers) think more about the local economy and local suppliers, i.e. minimize transportation costs, but of course only to the extent that the overall product costs less than it might otherwise.
I was thinking the same thing. If shipping costs make up a single-digit percent of the cost of most items–and fuel is only a percent of shipping cost –it’s barely going to be noticeable to the consumer. It’ll have massive implications for owner-operators and the industry overall.
I don’t think you can provide a good number as it will be product and location specific. Let’s just assume that the cost of transporting a trailer 1000 miles jumped from $1000 to $3000. If you’re hauling 2M worth of car parts in the container it’s basically an irrelevant 0.1% to tack on an extra $2000. If you’re hauling $5000 worth of lettuce though the price has now gone up 40%.
I heard a financial person throw out 40% as the cost of transportation for groceries recently. Not all of that is going to be fuel, but I suspect most of it is. And if fuel doubles in cost, that 40% might become 60 or 70%.
That doesn’t factor in the increased production costs as farmers have to pay more for their diesel too. Those will take a lot longer to show up, but they will eventually.
As a minor counter point – lowering the pace of inflation could prevent the increased raising of MSRP on autos so… Take advantage of that 0.25% extra in your online savings account and try to get a bigger down payment.
Please tell me this mythical bank that will match interest rate increases so I can move my money.
Any money market account will move rates up and down pretty much in concert with the fed rate.
There are quite a few that track quite closely. BankRate and other websites do a pretty thorough job of showing what banks are tracking closest.
I’m at Sallie Mae with a money market at 3.44%. It’s clunky but I have a checkbook so we have access any time.
Highly recommend moving to any kind of reliable online bank. You’ll have a notable impact on your savings compared to local banks unfortunately.
I’ll take a look. I had way too much money in a savings account that paid 5%…on the first $500 and since moved a big chunk to an Apple savings account that offers 3.4%
I have (free, high-interest) online savings accounts with Ally, Capital One, and Citizens Access. I move money between them at least monthly when rate differentials make it worthwhile.
AmExPersonalSavings is pretty on the ball as well with moving rates both up and down.
A bank with numerous branches such as Chase, forget about it. They only serve to take your money for basically free (or indeed charge you) and then lend it out at comparatively usurious rates.
Wealthfront will do it.
3.2%
Inflation, and to a lesser extent the entire current financial system, has little resemblance to what I learned in college in the late 80’s. If you take the historical definition of inflation, too much money chasing too few goods, that is not what we are experiencing now. It’s just too much money. Not sure how higher interest rates will help lower inflation, but most people I know are not spending money on “extras” as they don’t have much money left over from their monthly bills. Not sure how much longer this can go on, but I’ve been through two bad corrections, 01 & 08, and this one is shaping up to be worse. I sure hope I’m wrong.
The classic reason is that higher interest rates decreases the money supply. Combine that with your earlier definition of inflation…
That’s the problem. They are using a mechanism from the past to apply to a new problem. Seems like a pretty fast and hard recession is in the cards.
Volcker laughs.
“the cure for high prices is high prices”.
Can we change this from prices to inflation?
Asking for a friend
Unfortunately, additional taxes in the form of tariffs and what is probably a long term oil shortage are both contributors that interest rates will have little effect on. Once the higher costs drive us into full recession and lower demand for oil and imports we’ll be good though. /s/
At a base level, the act of increasing or decreasing the money available should be pulling on the supply and demand levers – i.e., increase the money supply to increase demand, and decrease the money to decrease demand (along with the related impacts on supply based on investment).
The problem is that with monopolization, the supply/demand curve is broken these days. High prices don’t mean more competitors entering the market and offering a better product at a competitive or lower price (increasing supply and reducing prices), because the giants can just crush the competition when they try to enter.
The economy we think we live in does not function with the level of wealth inequality we currently have, because all the rules start falling apart once someone has all the money.
I learned that at 10 years old, once we realized the game Monopoly wasn’t any fun once someone bought up all the properties…
This is why I trust economics data more than personal experience. Something taught early on as I grew up in a now dead auto town in Michigan. If I went by what my family and everyone we knew was feeling then the 90’s were a terrible time to live in the USA instead of one of the biggest boom decades and when we finally balanced the federal budget.
A note for the side that says people are still spending on extras. My wife and I are wrapping up a 2 week motorcycle trip through Maine, New Brunswick, and Nova Scotia. On the way up the coast and down the coast through Maine all the little towns were full of tourists. We thought scheduling after school was in session and before fall colors would have fewer crowds but every little town was a traffic jam of people shopping all those antique, kitsch, and art shops and sitting in way overpriced cafes. Not very nice hotels for $200 a night. Hotels priced double that or more with no vacancy. People are still spending money hand over fist on extras.
Edit: One thing to note was age. We are near 50 and stood out as young. Most of those tourists were retired seniors. A generation with money to burn and a ticking clock on their mortality.
Highest I have ever paid for a car loan was 5% for 60 months right out of college. I paid for 3 years then paid the rest off in a lump. I don’t think I would ever pay more than that for a car loan. At some point, when you look at the total cost of the loan, the car is never worth it.