The car market is both better than you’d guess and, if you’re a certain type of car buyer, much, much worse. The impact of tariffs and inflation is very real, but if you have enough cash or a juicy trade-in that you’ve already paid off, then you might be in the catbird seat. If you’ve got negative equity from a car you purchased during the pandemic, well, maybe the seat you’re in is neither cat nor bird adjacent.
A new report out from Edmunds will be the lead feature in today’s Morning Dump, because it shows how buyers of certain cars have found themselves in a fairly awful situation that’ll keep many of them saddled with huge interest payments. If some of those buyers were purchasing GM vehicles, it seems to have worked out for the company, which has posted a huge positive swing in profits.


One quirk might be how a new administration decides to deal with fuel economy rules, which are themselves a little screwy right now. Maybe China can come to the rescue? One Chinese automaker is offering American car companies help.
How Negative Equity is Fueling A New Cycle Of Auto Loan Debt
Didn’t have your morning coffee? No need, here’s a chart that’ll jolt you awake:

The car market has been on a bit of a roller coaster the last ten years. In 2016, carmakers sold more than 17.5 million vehicles, which was an all-time record. Many buyers keep their cars for 3-5 years before trading in for something new, right around the time their car payments are done. Unfortunately, that coincided with a pandemic that removed millions of new cars from production.
This created an unusual outcome. About a third of cars prior to the pandemic had negative equity when traded in, but the lack of new cars meant that the value of reasonably nice used cars skyrocketed, so individuals with trade-ins suddenly realized their cars were worth so much they could roll positive equity into their new purchase. If you timed it out just right, and bought something reasonably affordable, then you could have combined positive equity with low interest rates and saved yourself some money.
Or, as seems to have happened to a lot of individuals, that positive equity didn’t match up to the huge jump in new car prices (caused by low supply due to semiconductor shortages), so you ended up buying something expensive, stretched out your car loan to more than 60 months, and are still very much underwater. Now it’s 3-5 years later again, the market looks very different, and interest rates are going up.
Here’s our pal Jessica Caldwell from Edmunds explaining what it’s like to be one of those buyers now:
The financial consequences of rolling negative equity into a new auto loan have grown considerably in recent years. In Q3 2026, consumers who traded in an underwater vehicle and rolled their unpaid debt into a new loan financed an average of $57,235, up 44.1% from $39,732 in Q3 2019. Their average monthly payment climbed 47.4% over the same period, from $646 to $952.
Higher loan balances and interest rates are also driving up the total cost of borrowing. At an average APR of 8.1%, buyers who rolled over negative equity in Q3 2026 are on track to pay an estimated $16,610 in interest over the life of their loans, up nearly 83% from $9,093 in Q3 2019. Nine in 10 of these buyers (91.2%) financed their purchases over 72 months or longer, extending their payment obligations and increasing the risk of remaining underwater for longer.
The gap between these borrowers and those in the broader new-vehicle market illustrates just how costly rolling over negative equity has become. Compared with the average new-vehicle buyer in Q3 2026, consumers rolling over negative equity financed roughly $12,600 more, paid an additional $165 per month, and were on track to incur nearly $6,700 more in lifetime interest.
As I’ve said a bunch of times, this is all fine until it isn’t, but we’re already seeing signs of downclassing as buyers realize they can’t buy as much car as they thought they could. If we have a huge drop in employment or a prolonged down market, expect people to be talking about a huge rise in subprime and even prime automotive loan delinquencies.
GM Had A Bonkers Quarter, Buys Back Shares

Net income for GM grew by more than 150% in Q3 of 2026, compared to Q3 of 2025. That’s great, and the company expects net income attributable to shareholders to hit $8.9 billion to $9.5 billion this year. The company is still losing money in China, but the combination of earnings from subscriptions (OnStar and SuperCruise) as well as from trucks has helped keep profits up.
Here’s GM CEO Mary Barra in a letter to shareholders:
GM is performing well, and we are working hard to continue our momentum despite growing inflationary pressures through strategic investments in new products and services, and through improved quality and operating efficiency.
Over the next several years, our portfolio will only get stronger as we complete the launches of the all-new 2027 Chevrolet Silverado and GMC Sierra light duty pickups and follow them with our next-generation heavy duty pickups, our next-generation full-size SUVs, all-new Cadillac sedans and crossovers, and more.
Given that trucks and software are helping make money, new trucks with better software seems like a good strategy.
The Board of Directors also approved a $20 billion multi-year share repurchase plan, as the company seems to think its current share price is lower than the true value of the company.
This didn’t make everyone happy, with UAW President Shawn Fain, who sent out a statement (via the Freep) decrying the decision:
“Let’s be clear about what stock buybacks really are. They are a form of legalized mass looting, sending billions of dollars generated by the working class directly to Wall Street investors who’ve never seen the inside of a factory,” Fain said. “Why don’t 80% of GM’s autoworkers have a pension and retirement healthcare, as they did for half a century? Because someone on Wall Street is collecting their pension check in the form of a (expletive) stock buyback. Why is GM nickel and diming their retirees while lavishing shareholders with billions? Because this company has sold its soul to Wall Street.”
GM countered that they’ve invested billions of dollars and also return the highest profit sharing in the industry.
CAFE Rules Are Going To Make Things Screwy
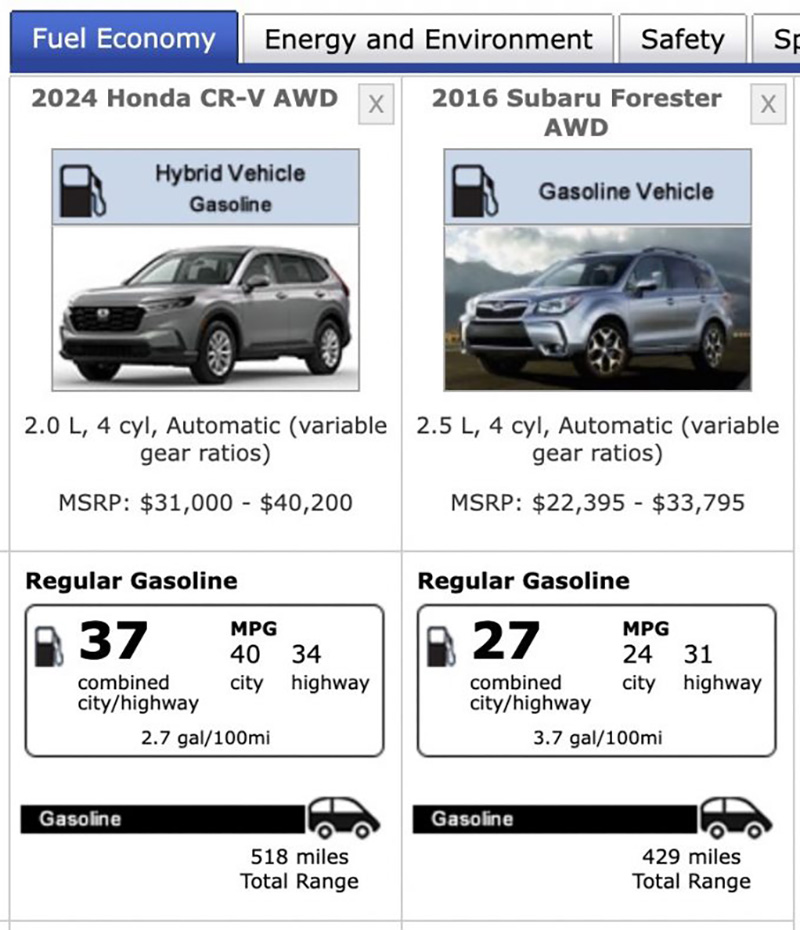
Between the current administration lowering fuel economy standards and Congress essentially removing all penalties for violating Corporate Average Fuel Economy (CAFE) standards, there’s nothing any current automaker probably has to do in order to be compliant. Or, at least, to pay for being non-compliant.
The one change that’s positive, though, is tweaking the rules about what counts as a “passenger vehicle” and what counts as a “light truck.” Starting in 2030, more actual cars will be classified as cars. This will impact everyone, though it won’t impact every car equally, as Automotive News explains:
Unlike the light truck fleet, the agency divides the passenger car fleet into two sections: domestic and imported.
Domestic vehicles have at least 75 percent of the cost to the manufacturer attributable to value added in the U.S. or Canada.
Federal statute requires that domestic passenger car fleets meet a minimum CAFE standard, calculated as 92 percent of the average fuel economy projected for the entire domestic and imported passenger fleet. The imported fleet does not have to meet that floor.
Now that more vehicles will be considered passenger cars, manufacturers will likely be paying even more attention to the stringency of the domestic fleet rule.
Depending on what happens to tariffs and CAFE penalties, does this mean that it’ll suddenly be better or cheaper to build some vehicles outside of the company? Making cars is a headache.
Could Chery Help Automakers In The United States?
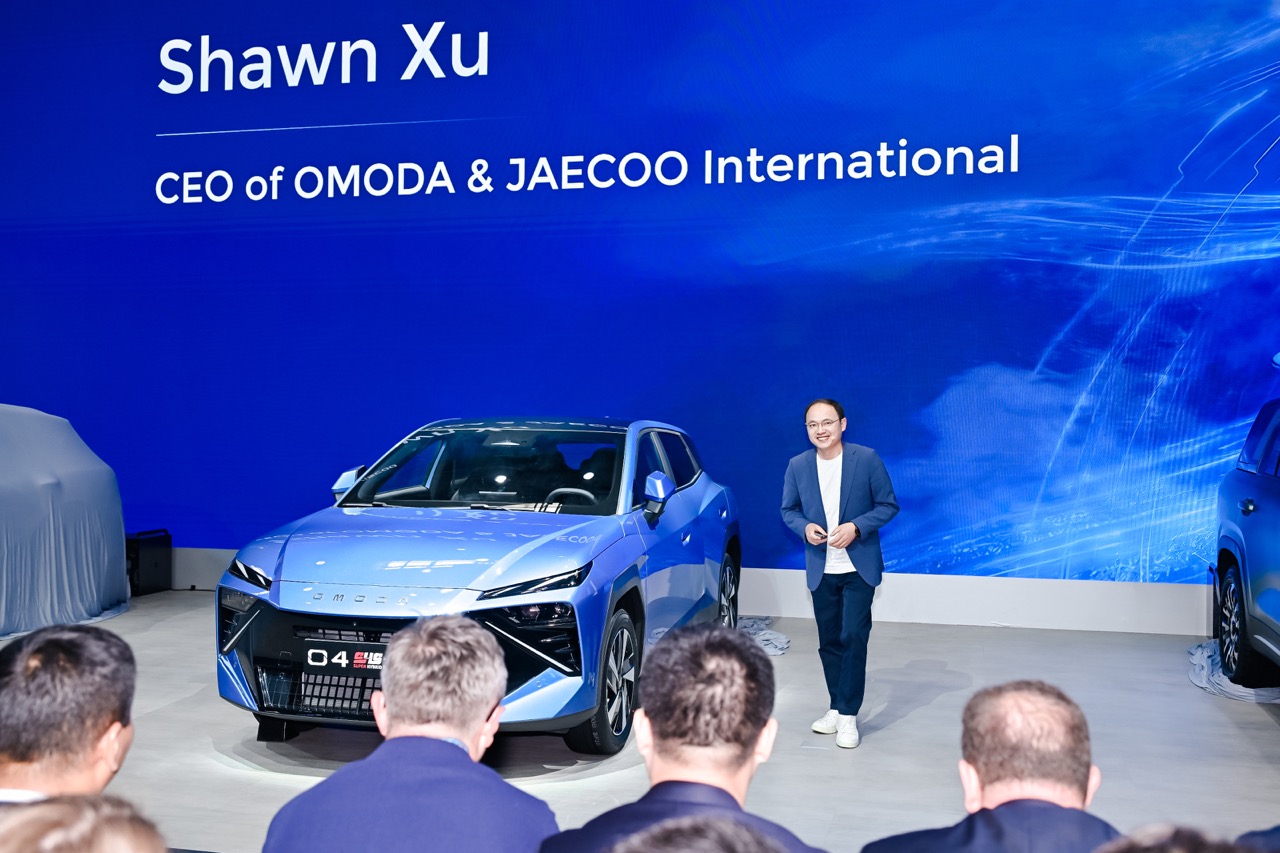
Chery has been one of the more successful automakers abroad, and now even has the honor of making Britain’s best-selling car thanks to the success of the Jaecoo 7. An executive for the company, VP Charlie Zhang, just said, hey, maybe Chery can help out some US automakers.
“The US, obviously, we are trying to look for different options there,” Zhang said, emphasising Chery’s flexibility.
“We’re very open to different options, even a potential partnership with American automakers,” he said. Zhang’s comments are some of the clearest yet about Chery’s American ambitions, although he did not go into specifics about the kind of partnerships he envisions.
Zhang said he was confident that Chery would find a way to target the US, saying it would be possible to build a car that was not reliant on Chinese hardware or software.
“Definitely from a technical point of view, we will be able to find a China-free solution in terms of hardware and software,” he said.”
So, no hardware or software from China … so what is the partnership, exactly?
What I’m Listening To While Writing TMD
SWG sent me an Instagram reel of Ben Folds Five in one of their earliest TV appearances, performing “Underground” on Late Night with Conan O’Brien back in 1995. It turns out, someone has just put a much higher-quality rip on YouTube, so now you can enjoy the whole thing.
The Big Question
What’s the best deal you’ve ever gotten on a new car? What’s the worst?
Top graphic images: stock.adobe.com; DepositPhotos.com


I’ve usually managed to get really good deals on my new car purchases – otherwise, I just don’t buy them in the first place. Highlights being 1/3rd off my ’08 Saab 9-3SC in the Saab firesale, 1/3rd off my ’18 Fiata as a leftover, $12K off my ’16 M235i, $6K off my ’11 328!, $6K off my ’17 GTI (which I then sold for what I paid for it four years later, so the best overall deal but the worst decision).
Worst new car deals were my first new car, a leased ’02 Golf TDI (I got screwed), and I only got $1000 off my ’13 500 Abarth, but it was cheap to start with so not much margin comparatively. I’ve lost far more money on sundry used cars than new ones.
I loved buying new cars when they sold what I wanted – especially those two Euro-delivered BMWs. That is like a cocaine habit, expensive but you just want to keep doing it. I should probably be thankful for the direction cars have taken in the past decade or so, has eliminated all desire for anything newer than my pair of 2011 BMWs.
TBQ: My wife and I decided to go test drive some 3 row family haulers for her Mazda CX5 Replacement in March of 2021. I had built up a decent bit of savings from all of the OT I had to work during the pandemic shutdown and didn’t really like her ’14 CX5 since it was a base, base, spec she bought because she was in a position and needed a car. We went and looked at a few options, with the CX9 being the last stop. I was dead set on getting a lightly used one because I did not want to eat the depreciation hit from a new car. The local dealer had 12 new CX9s on the lot they were desperate to sell, 1 used one. I was planning on casting a wide net to find the spec used one that we wanted, however the sales team was insistent we test drive a new car.
Without negotiating any on the new car price we walked out with a $5k discount and above market value on our trade in. When I went to collect the license plate for it at the end of the month, they had 0 CX9s on the lot, and the salesman said they sold all of them that weekend we bought ours. This was when I knew the market had turned from a buyers’ market to a sellers’ market.
Have never bought a brand new car and not sure I would. Even the R3X if they come out unless it is 45k or less I cannot see spending more on a new car when slightly used in a year or 2 could be half that price.
Best: $4K off of a 2001 Toyota Highlander because it was dark green, 2WD, and at a dealership in the California desert. Still driving it.
Worst: MSRP for a 2004 Acura TL. I fell in love. Got $10K earlier this year from the state to buy a BEV and dismantle the Acura (RIP).
The best advice for some with negative equity in their car is the most obvious advice- Keep it until you pay off the loan or at least are no longer underwater. If you are in that situation and the car gets totaled you don’t really have any “good” options. You probably can’t afford frequent repairs while also paying off the loan for your dead car, so that makes buying something really cheap on Craigslist or FB Marketplace risky. The safest way out of that mess is probably to buy a new car with more poverty switches than real switches and ride it out.
Fortunately, even the cheapest base model cars sold today are very nicely equipped compared to base model econoboxes from a generation ago.
Never forget that 50% of people are below average. And these days, that average is not high to start with. And dropping.
But she told me average was good enough. And I’ll see myself out now haha.
I’m not sure the best I’ve gotten a few cars about half off of sticker. Others close to half off. My Jetta TDI sticks out to me as a strange good good deal. I paid about $14.5k it stickered for close to $24k. The buy back a few years later was close to sticker. The worst deal I ever got was by far a Subaru I didn’t want to buy during the worst time to buy. I only got $500 to $1k off sticker. For what was the one of the worst new cars I’ve ever had. It was just bad because they are all bad.
I’ve never bought a new car, which overall strikes me as a pretty good deal.
The only winning move is not to play.
same here. not really poor but for some reason constantly being in the used car market and knowing the prices it was never a dilemma for me. and I do not plan on buying a new one especially nowadays
Happy PHP crazy update day! Hope y’all got your patches done. This exploit is… wow.
Best deal was the 2019 outback we bought as one of the last on the lot. Subaru was sure the new one with the big screen was going to be a hit, I was sure I wanted the buttons. I think it was $21k out the door, and we were able to pay cash from my wife’s deployment (so that was tax free too).
These “many” are about 16-25% of the car-buying market (depending on whether you want to count it by individuals purchasing, fleet purchasing, leases, or units on the road).
The median car in the US right now is… 12 years old. Survivorship bias is what it is (cars will attrit before hitting 12 years), but fundamentally this means that the typical car in the US gets replaced when more than 12 years old (the number of cars continues to grow, but it may look like a family buying a 5-year-old sedan from a buyer buying new, to hand off their 17-year-old car to their teenage driver, thus to some degree preserving the median while adding a new car to the market)
The lesson here is “if buying a luxury good – which a new car is – I don’t feel bad for you.”
TBQ: Wait, y’all are buying new??
A lot of people aren’t liquid enough to play the used market effectively. A LOT of people.
TBQ: Got my 2018 VW Golf Sportwagen S 4Motion 6-Speed for over 20% off MSRP, 25k exact MSRP, sale price of 19.6k, OTD around 21.3k if memory serves. Certainly helped that my perfect trim/spec combo was the antithesis of American taste – Blue over tan cloth, manual station wagon from VW.
My ’22 CX-30 turbo I got to replace the Golf was a decent deal in the sense that I got it at sticker at a time when used equivalents with 15k miles were 2k over, and I custom ordered the exact spec I wanted, Polymetal Gray (basically blue) over Tan pleather. I certainly have a type, although both would have been green over brown if that was available.
Best deal I got on a new car was when I was in college. 2006 Honda Civic LX. My credit union had an auto buying service. I sat down, told them the make, model and trim. They located one a couple states away and had a fixed price well below MSRP. I got it delivered to my driveway and I had preferred financing from the CU. Hell of a deal for a 23 year old buying their first new car. No experience has matched that since for me.
I did audits of credit union lending programs at a previous job, no graph about the stupid auto loan decisions of people can ever surprise me.
I used to be in business lending, it was borderline horrifying, people with abysmal personal finances (6 figure car loans, 6 figure credit card debt) would submit loan applications to buy a new small business with a totally straight face, acting as though they didn’t recognize any potential problems, then would get angry and belligerent when the loan was inevitably declined
What is grimly funny about the latest ignorant rant from this blowhard is that one of GM’s largest stockholders is the union health care retirement fund. The buybacks will directly benefit the retirees of his union.
Well said, messaging and drumming up outrage at “the other party” keeps the President elected cycle after cycle. Fain is a politician like any other, and as such, I treat his words with about the same amount of value. He’s also willfully ignoring the fact that pensions and retirement healthcare are very rare these days, and that GM has 401k contributions and matching that is in place explicitly to fill the gap left by undoing pensions. Also the fact that UAW collective bargaining over decades has resulted in this current retirement package being the approved and agreed upon one, but OK, lets blame GM for that instead.
I have friends who have worked as engineers in UAW plants, and those who have worked in non-UAW plants, myself included. All I will say is that the efficiency and speed of progress and improvements in manufacturing in the non-UAW plants is far greater.
He’s not ignoring that pensions are rare, he’s explicitly stating they are rare. And defined benefits are rare because of corporate greed that attacked them on both sides: not wanting to have to pay for them, and recognizing that moving everyone into a 401k is going to juice the market as a whole.
Anecdotal, but in my experience even the working conditions, and cultural environment for the hourly folks is better in non UAW Automotive Plants. It seems to me that unless you have been a part of a UAW plant for 25+ Years, you just get hosed by the old timers.
Not unique to the UAW, it is a major fault, maybe the major fault, of unions. Seniority trumps all and the current membership will sell the future membership down the river if it helps them now.
It is definitely not unique to the UAW, but in my experience working as a salaried “company man” with multiple different Unions, they were the worst about it. In fact they are the only one I don’t like and think actively ruin it for the company and the membership
Similar experience, plants I worked at were UAW and USW. The UAW was much harder to work with or a daily basis as a supervisor/engineer.